
Download the 11.20.26 Q3 2026 Dynamic Investing Insights for advisors’ use with clients
By Kostya Etus, CFA®
Chief Investment Officer, Dynamic Asset Management
“Stick to the fundamentals. That’s how IBM and Hilton were built. Good things, sometimes, take time.”
– Lou Mannheim (Hal Halbrook), “Wall Street,” 1987
Market Review
Markets have been caught in a summer lull, with relatively flat returns since around June. I’m reminded of an old market adage, “sell in May and go away,” which insinuates seasonally weaker returns during the May to October period. Now, as we move into the cyclically-stronger holiday season, there may be an opportunity for the market to be reinvigorated.
That said, despite some weakness in the third quarter driven by higher interest rates, global markets are still up double-digits on the year (through the end of September). More importantly, market breadth has widened with more asset classes and sectors outperforming and market concentration has eased, creating a potentially more stable environment moving forward.
In terms of what to expect for the last stretch of 2026 and beyond, we look at the key drivers of returns to gain some insights:
- Economic Data. Latest Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) inflation data showed a jump in September inflation above previous months and above expectations, caused by continued conflict in the Middle East. Meanwhile, the U.S. Gross Domestic Product (GDP) data showed the economy grew at 3.4% in the third quarter, well above previous quarters and above expectations. The combination of higher inflation and a strengthening economy implies the Federal Reserve (Fed) may continue to increase interest rates in the future.
- Interest Rates. We had our first interest rate hike in three years in September with the Fed citing elevated inflation; a healthy labor market guided the decision. The Fed kept rates unchanged in October, but given recent data, the expectations for a hike at their next meeting in December are nearly 80%. Furthermore, rising interest rates are not a U.S. phenomenon, with the European Central Bank (ECU) as well as the Bank of Japan (BOJ) increasing their policy rates as well. These trends have sent 10-year U.S. Treasury yields to more than 5% for the first time since 2007. This creates headwinds for stock, bond and real estate markets as funding becomes harder to source for consumers and businesses alike.
- Corporate Earnings. It’s not all gloom and doom as there’s a bright spot for the markets in the form of earnings growth. Analyst expectations for third quarter earnings growth are nearly 30%. If realized, it would mark the third consecutive quarter of growth over 25%. Additionally, like what we’ve seen with stock prices this year, earnings growth has also broadened beyond the technology sector with other areas of the market starting to grow their bottom line. Given earnings fundamentally drive market returns, as long as they remain healthy and growing, stock prices should have a strong tailwind at their backs.
As uncertainty subsides around geopolitical conflicts, mid-term elections and interest rate moves, the skies should start to clear and offer more stability for the markets through year end. Particularly as consumers forget about the problems of the world and open up their wallets for the holidays, supporting strong earnings growth!
Asset Class Returns through Q3 2026
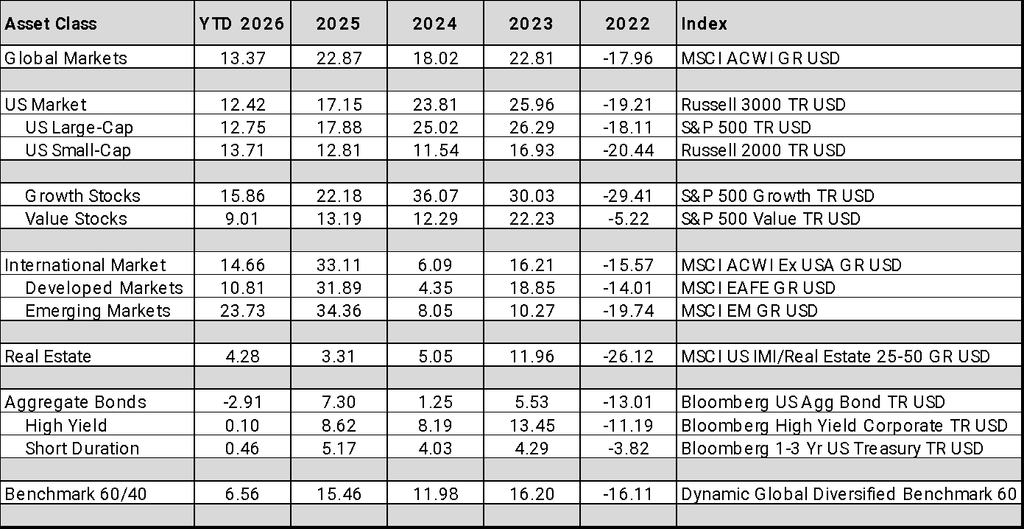
Source: Morningstar Direct as of 9/30/2026. Past performance does not guarantee or indicate future results. Dynamic Global Diversified Benchmark 60 consists of 45% Russell 3000 TR USD, 15% MSCI ACWI Ex USA GR USD, 40% Bloomberg Universal TR USD.
Key Takeaways:
- Investing is a long-term game and looking at the shot-term doesn’t always tell the full story.
- The long-term fundamental drivers of returns focus on the underlying financial structure of companies, not short-term market noise.
- The best way to defend from concentration, cyclicality and corrections is through diversification.
Risk vs. Time Horizon
One of the most common investment concepts is that stocks are riskier than bonds. And this is easily observed on any given day when you compare performance between the two asset classes. But investing is a long-term game and looking at the short term doesn’t always tell the full story.
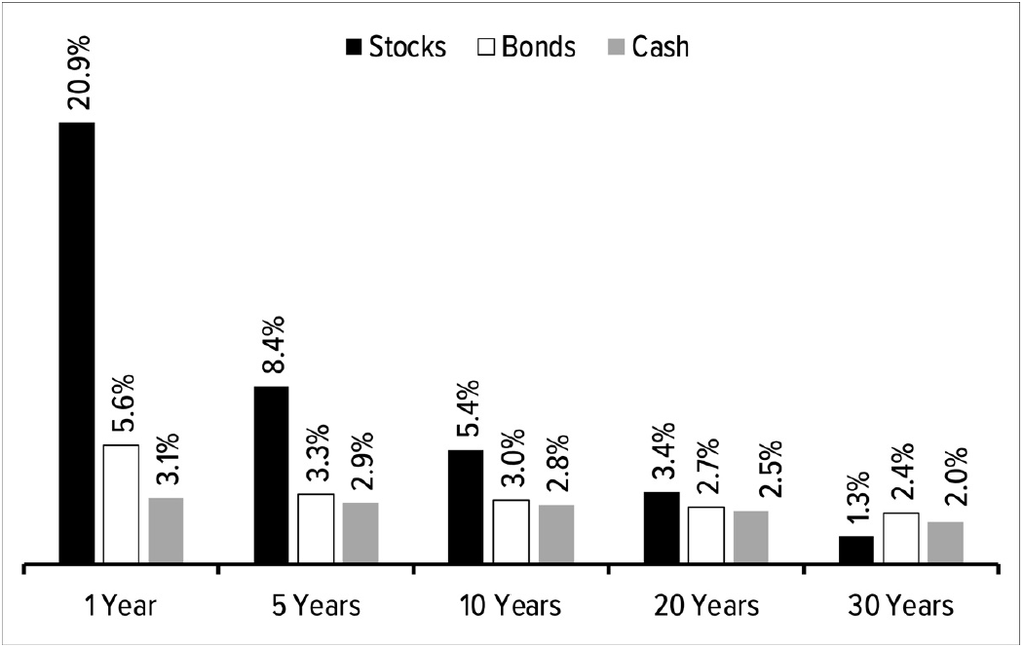
The chart blow features the risk (standard deviation) of monthly returns for stocks, bonds and cash over various periods. Here are the key insights:
- Short Term. The stock market is very volatile in the short-term. A standard deviation of 21% over a one-year period means that if the average annual return for the stock market is 10%, in any given year it will range from positive 31% to negative 11%. But those are average deviations; there are often outliers. For example, the best 12-month return for the S&P 500 over the evaluation period was +163% and the worst was -68% — that’s quite the range! This is often the risk investors think about and try to diversify with bonds or cash to help dampen the deviations of returns.
- Long Term. Across the time horizon, volatility in the stock market starts to fall drastically, while bond and cash risk remains relatively stable. We often talk about how investing is a long-term game, and it’s best to ignore the short-term noise, this is the data that backs it up. Over a 30-year holding period, the stock market is actually lower risk than bonds or cash! The problem is that emotions often get in the way of holding through the entire period. As referenced above, losing 68% of your investment value is hard to accept.
- In the Middle. There’s no one-stop solution to investing and each situation is different. Most investors lie somewhere in the middle. Given that volatility is based on investment time frame, that’s often a good place to start. The longer your time horizon, the more comfort level to invest more in the stock market. As the time-to-retirement shortens, the additions of bonds/cash help defend against shorter-term volatility and protects your investment. Ultimately, staying balanced and diversified is the best way to reach your investment goals.
Asset Class Volatility by Holding Period
S&P 500, 5-Year Treasuries, 1-Month T-bills, 1926–2024
Source: “Risk and Reward: How to Handle Market Volatility and Build Long-Term Wealth,” by Ben Carlson (May 12, 2026), Figure 12.6 on page 113. Source: Returns 2.0.
Voting Machine vs. Weighing Machine
Looking back over the past 10 years, we’ve had some sensational market-moving events, including Brexit, China trade war, COVID-19, post-pandemic inflation surge, Fed rate hikes, AI boom and Russian invasion of Ukraine, to name a few. And yet, over 10 years, the U.S. stock market (S&P 500) has managed to achieve returns more than 15% per year. On a cumulative basis, that’s over a 300% return across that period, meaning an investor would have quadrupled their money! How is this possible, and how does the market continue to grind higher over time?
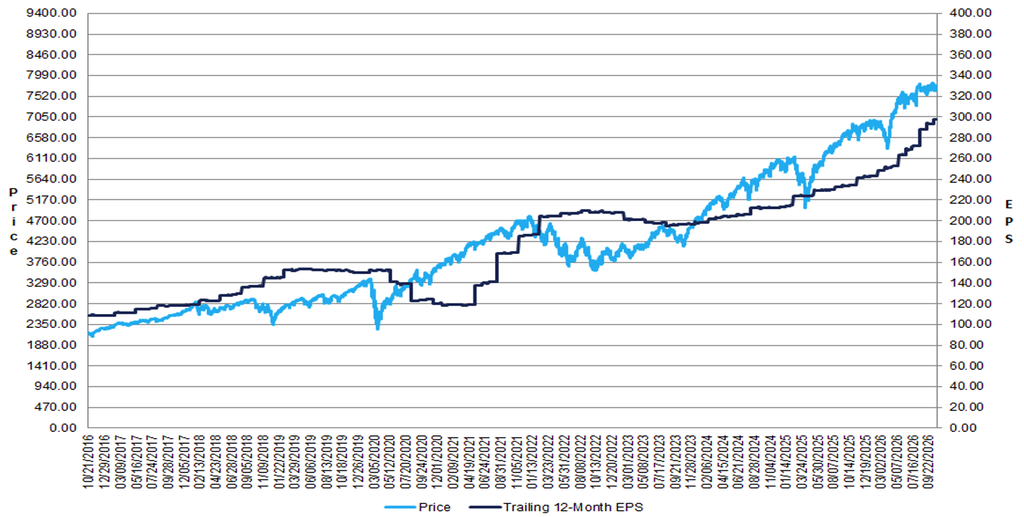
To answer that question, we look at the chart below which shows the price of the S&P 500 over the past 10 years compared to earnings growth of the companies within the S&P 500:
- Voting vs. Weighing Machine. A famous quote from legendary investor Ben Graham states, “In the short run, the market is a voting machine, but in the long run, it is a weighing machine.” The voting machine represents short-term market noise, as stock prices bounce around based on a popularity contest, reacting to dramatic headlines, fear and knee-jerk reactions. The weighing machine means that in the long-term, the market removes emotions and weighs the fundamental drivers of returns to determine where prices should be.
- Fundamentals. The fundamental drivers of returns focus on the underlying financial structure of companies, including earnings, cash slows, profit margins, debt, valuation multiples, etc. But if you pare down any company to its bare essentials, the thing long-term investors care most about (and thus what the market cares about) is how much money companies are making.
- Investing for the Long-Term. As the chart shows, over the past 10 years, earnings have steadily increased, albeit with some volatility. That said, it is nowhere near the volatility exhibited by the market price (blue line), as it is susceptible to short-term noise. But if you adjust your focus and look at the full picture, you’ll notice despite the path to get here, both earnings and price start and end in about the same place. Staying invested and diversified for the long-term, while ignoring the short-term noise, is the best way to achieve your investment goals.
Market Earnings vs. Price
S&P 500 Change in Trailing 12-Month EPS vs. Change in Price: 10 Years
Source: FactSet Earnings Insight, 9/11/2026.
Concentration vs. Diversification
We know that the market has been fairly concentrated in the previous few years. Meaning that a relatively small number of companies have been responsible for the majority of growth in the market. The outperformance has been primarily driven by the artificial intelligence (AI) boom and the mega-cap technology growth stocks that benefitted. This has resulted in fewer companies representing a larger portion of the market itself and increased inherent risk. If any of those large companies have meaningful pullbacks, they will take a larger chunk of the market down with them, causing a potential market correction.
However, as AI becomes more mainstream and valuations become stretched for the companies at the top, a regime change begins to emerge. A great rotation of sorts, where smaller companies begin to reap the benefits of AI and grow their profits, thereby increasing stock prices. Meanwhile, the tech giants are struggling to keep up with lofty earnings expectations and may start to come down to planet Earth in terms of stock prices.
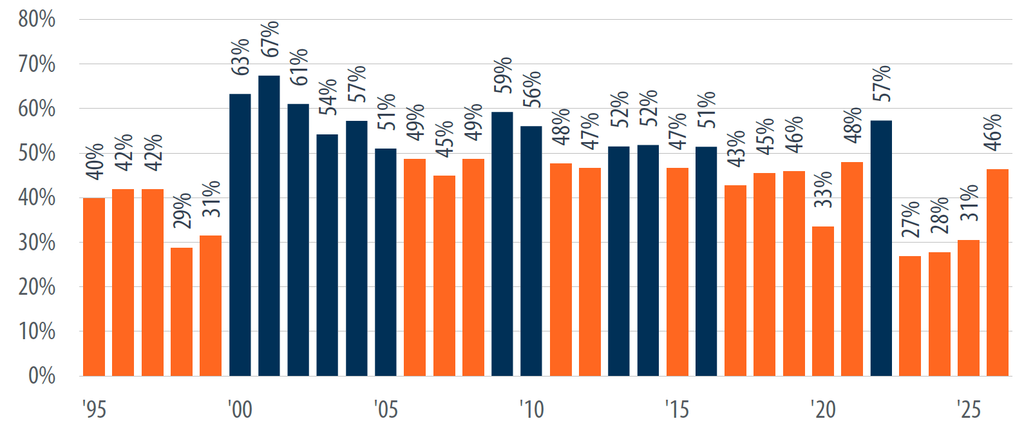
But how can we evaluate the amount of broadening happening in the market leadership? One way is to look at what percentage of stocks within the S&P 500 are beating the index itself (chart below). Let’s review the key insights:
- The Last Three Years. The period from 2023-2025 has some of the lowest percentages of companies beating the index that we’ve seen since 1995. In 2023, we had the launch of AI, which gave rise to the Magnificent 7, carrying the bulk of the index for nearly three years, and leaving the other 493 stocks behind. But finally, in 2026, we are seeing a broadening into other areas of the market, with more companies starting to outperform the index.
- We’ve Seen This Before. The last time we saw such a narrow leadership was in the late 1990s… remember the Tech Bubble? And that period was followed by a fairly sharp multi-year broadening in market participation (blue bars represent leadership more than 50%). Such a shift could be underway today, with 46% beating the index in the first half of 2026. This is a great reminder that just like anything else in the markets, cyclicality is present. If you average all the years on the chart, you get about 47%. Thus, when the percentage falls well below, there’s a natural tendency to eventually spring back up.
- Diversification Protects from Concentration. The best way to defend from concentration, cyclicality and corrections is through diversification. By allocating beyond the top seven companies, beyond the technology sector, beyond mega-cap growth stocks and even beyond the S&P 500 – you can dampen an adverse shift in any one area of the market, protecting your portfolio and your wealth. Staying diversified and invested for the long term is the best way to reach your investment goals.
Stay diversified, my friends.
Percentage of S&P 500 Index Members Outperforming the Index
1995 – 1H 2026
Source: Capital IQ, First Trust Advisors. Data from 12/30/95-6/30/26.
As always, Dynamic recommends staying balanced, diversified and invested. Despite short-term market pullbacks, it’s more important than ever to focus on the long-term, improving the chances for investors to reach their goals.
Should you need help navigating client concerns, don’t hesitate to reach out to Dynamic’s Asset Management team at (877) 257-3840, ext. 4 or assetmanagement@dynamicadvisorsolutions.com.
Disclosures
This commentary is provided for informational and educational purposes only. The information, analysis and opinions expressed herein reflect our judgment and opinions as of the date of writing and are subject to change at any time without notice. This is not intended to be used as a general guide to investing, or as a source of any specific recommendation, and it makes no implied or expressed recommendations concerning the manner in which clients’ accounts should or would be handled, as appropriate strategies depend on the client’s specific objectives.
This commentary is not intended to constitute legal, tax, securities or investment advice or a recommended course of action in any given situation. Investors should not assume that investments in any security, asset class, sector, market, or strategy discussed herein will be profitable and no representations are made that clients will be able to achieve a certain level of performance, or avoid loss.
All investments carry a certain risk and there is no assurance that an investment will provide positive performance over any period of time. Information obtained from third party resources are believed to be reliable but not guaranteed as to its accuracy or reliability. These materials do not purport to contain all the relevant information that investors may wish to consider in making investment decisions and is not intended to be a substitute for exercising independent judgment. Any statements regarding future events constitute only subjective views or beliefs, are not guarantees or projections of performance, should not be relied on, are subject to change due to a variety of factors, including fluctuating market conditions, and involve inherent risks and uncertainties, both general and specific, many of which cannot be predicted or quantified and are beyond our control. Future results could differ materially and no assurance is given that these statements or assumptions are now or will prove to be accurate or complete in any way.
Past performance is not a guarantee or a reliable indicator of future results. Investing in the markets is subject to certain risks including market, interest rate, issuer, credit and inflation risk; investments may be worth more or less than the original cost when redeemed.
Investment advisory services are offered through Dynamic Advisor Solutions, LLC, dba Dynamic Wealth Advisors, an SEC registered investment advisor.
Photo: Adobe Stock